
Appraisal for Multiple Heirs Estate Orlando: How to Agree on Value
A shared appraisal is a practical starting point when heirs disagree about an inherited home’s value. For an appraisal for multiple heirs in an Orlando estate, agree on the property, valuation date, and purpose, then use one independent appraiser so everyone receives a report based on the same assignment. That shared reference can ground discussions about a sale or distribution in evidence.
Heirs may view the property differently. One may focus on its potential sale price, while another weighs its condition, family history, or a fair division of the estate. A clear valuation helps separate those concerns from the question of the property’s value for estate purposes.
This article explains how heirs can address appraisal disagreements, when inherited property may need an appraisal, and how estate and probate valuations work. It also covers why the effective date matters, what a retrospective appraisal can establish, and how a defined scope helps everyone begin with the same question.
Table of Contents
Can You Get a Date-of-Death Appraisal Years After Someone Dies?
Yes. A retrospective appraisal can estimate an inherited property’s fair market value on the owner’s date of death, even when ordered years later. The appraisal’s effective date is historical, not the inspection date or the date heirs request the report. This distinction matters when estate records, a later sale, or the property’s investment history depends on its value at death.
Online estimates and real estate agent valuations can provide context, but they aren’t substitutes for a retrospective appraisal. Online tools use available property and market data, while an agent’s opinion may focus on a potential listing. An appraiser analyzes the property and evidence relevant to the requested valuation date.
The valuation usually begins by identifying the correct date and purpose. A date-of-death appraisal estimates fair market value as of the decedent’s death. In limited estate-tax situations, an executor may elect an alternate valuation date six months following death. That election is available only when the estate must file Form 706 and the election reduces both estate tax and the estate’s total value. It isn’t a general option for every inherited home.
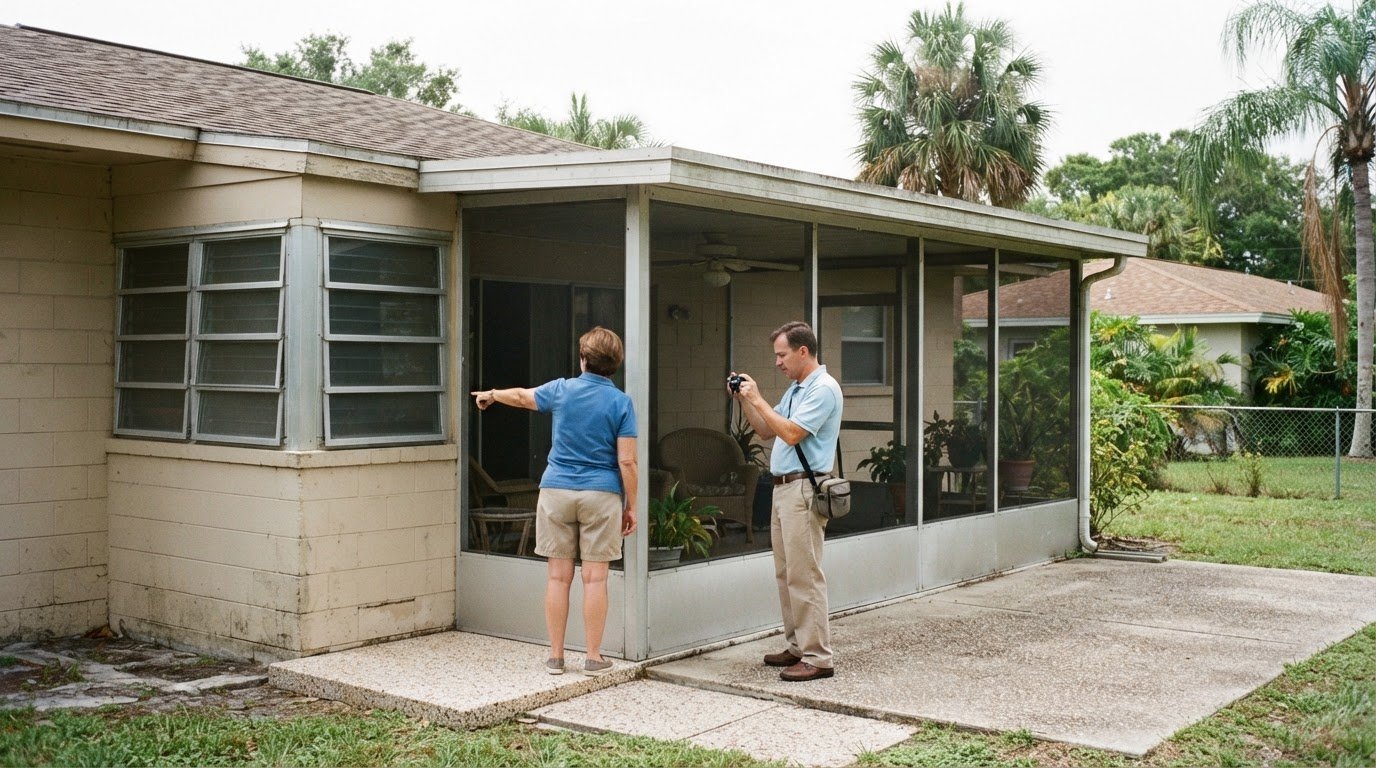
A retrospective appraisal can help when an estate is settled long after the owner’s death. The appraiser considers historical evidence, including comparable sales and listings, property features, and market trends relevant to the effective date. A current inspection can document the property’s condition, but current conditions shouldn’t be mistaken for its condition at death. Records and photographs from around that date can help show what changed afterward.
Timing can affect the evidence available. A date-of-death appraisal should be completed before the inherited home is listed or major changes are made. If the home has already changed, the appraisal still focuses on the historical date and considers supporting information about the property then. The report can describe its analysis, valuation method, and supporting data, giving heirs a reasoned basis for understanding the conclusion.
Consider a home valued at $400,000 on the owner’s date of death and sold six months later for $410,000. A property's value at death and its later sale price can both matter when calculating taxable gain. The example shows why the historical market value matters: using the later sale price as though it were the value at death would change the comparison.
A retrospective appraisal is distinct from a current market estimate. It addresses a defined property, purpose, and effective date, then weighs evidence tied to that date. For heirs, a clear valuation can support estate discussions while keeping historical fair market value separate from today’s listing expectations or later improvements.
What Happens If Heirs Disagree About the Appraised Value?
Start with one independent appraiser and a shared scope that identifies the property, valuation date, and purpose. In Florida, the resulting value can document an estate asset and inform distribution discussions. It may also help establish the inherited property’s basis for calculating capital gains if it’s later sold.
Coordinating an Appraisal Among Heirs
Coordinating one appraisal means heirs agree on the assignment before the valuation is completed. Everyone receives one report based on the same property, date, and purpose, rather than separate opinions built around different assumptions.
The executor can organize the assignment and include the estate attorney when the report’s intended use needs clarification. Before the appraisal begins, define whether it will address value at the date of death or another relevant date. Identify the property and explain how the report will support estate discussions. A clear scope gives the appraiser consistent instructions.
Heirs may disagree because they’re weighing different evidence. One may focus on a potential listing price, while another points to repairs or improvements. Record those concerns as specific property facts for the appraiser to consider. The appraiser’s research should explain how comparable sales, property condition, and market evidence support the conclusion, rather than simply splitting the difference between relatives’ estimates.
If an heir identifies a factual error, such as an incorrect property feature, raise that specific issue for review. A difference of opinion alone doesn’t show that the analysis is wrong. The report’s reasoning and evidence give the executor and heirs a common reference for discussing value instead of relying on competing assumptions or personal knowledge of the home.
Property Value in Heir Distributions
An appraisal assigns a supported value to the inherited property; it doesn’t determine each beneficiary’s legal share. Heirs can use a shared valuation in distribution discussions, while the estate’s governing documents and administration determine how assets are allocated.
For example, beneficiaries might discuss whether one heir keeps the home while others receive different estate assets. A reliable property value makes that conversation more specific, but the appraisal alone doesn’t establish whether the arrangement is permitted or how the estate must carry it out. The executor and estate attorney can apply the valuation within the estate’s distribution process, and families often rely on estate planning practices like Northeast Legal Team to ensure asset division aligns with governing legal documents.
The valuation date also matters for capital gains basis. A date-of-death appraisal can establish the property’s fair market value when the original owner died, which may serve as an heir’s stepped-up basis. If the property is later sold, the difference between that basis and the sale price is relevant to calculating gain, subject to other adjustments.
Keep the report, its effective date, and the supporting valuation evidence with estate records. If a shared assignment is the right next step, a defined inherited-property appraisal can give heirs a consistent valuation to discuss.
Do You Need an Appraisal When You Inherit Property?
An appraisal can document an inherited property’s value for estate administration, distribution, or tax reporting. Whether one is needed depends on the estate’s purpose, filing requirements, and the records beneficiaries must support.
When an Estate Appraisal Is Required
A date-of-death appraisal establishes real estate’s fair market value on the owner’s date of death. In Florida, it’s required for federal estate-tax purposes when the gross estate exceeds the federal exemption threshold. That federal filing trigger doesn’t mean every inherited home automatically requires an appraisal.
For an estate required to file IRS Form 706, a qualified appraisal can support the reported value. Schedule F of Form 706 requires detailed documentation of personal property, including vehicles, for estates exceeding the federal exemption threshold. The property type and filing purpose determine which valuation records are relevant.
An appraisal may also help an executor document estate assets or explain a proposed distribution among beneficiaries. A certified, professional appraisal provides a reasoned value and supporting documentation, rather than relying solely on an online estimate. The executor can define the report’s intended use so the effective date and analysis address the estate’s actual need.
Estate Appraisal Timing
An estate appraisal’s timing includes the property inspection and the later research and report preparation. A property inspection takes 20-45 minutes, while the complete appraisal involves additional analysis of property features and relevant market evidence.
For an Orlando home, the appraisal process depends on the assignment’s scope, access, property condition, and supporting records. A historical effective date also requires research into the market at that time. The inspection alone doesn’t represent the full valuation process.
Documentation helps make the analysis specific. Useful records can include photographs showing the property near the valuation date, renovation information, and estate documents identifying the required date and purpose. If a home was renovated after the owner’s death, for example, records can help distinguish its earlier condition from its current condition.
Keep the final report with the estate’s filing and distribution records. It should identify the property, valuation date, method, and fair market value conclusion, with evidence supporting the analysis. If the estate holds multiple assets, separate valuation records can clarify which conclusion applies to each one.
A qualified appraiser’s report can also help beneficiaries understand how the valuation was reached. Clear documentation connects the conclusion to the property’s characteristics and the relevant market evidence. That makes the appraisal useful beyond a single filing, including later estate discussions about value, distribution, or a potential sale.
USPAP-compliant appraisal reports
USPAP sets minimum standards for conducting appraisals. For an estate report, those standards help organize the appraiser’s analysis, supporting evidence, and value conclusion. Heirs can use a consistent framework to understand how an opinion was reached, rather than treating the final figure as an unsupported estimate. The report’s purpose and effective date still matter.
A useful estate report connects its conclusion to the assignment. It identifies the property or assets being valued, the date of value, the valuation method, the appraiser’s qualifications, and the fair market value opinion. For a date-of-death assignment, the effective date is the decedent’s date of death, even if the report is prepared later. These details distinguish historical value from current market value.
For Orlando heirs, choose an appraiser with relevant experience valuing the type of property involved and the ability to explain the method and evidence used. The report should identify the appraiser’s qualifications and show how property characteristics and market research support the opinion. That clarity matters when beneficiaries, an executor, or a probate court needs to understand the valuation.
USPAP compliance concerns the appraisal process and report, not whether every heir agrees with the conclusion. A report can explain why the appraiser selected particular comparable sales, considered specific property features, and reached an opinion. If an heir spots a factual error, such as a misstated feature, that issue can be distinguished from disagreement with the appraiser’s judgment.
Estate records may serve different purposes. A report prepared for probate distribution may also help document value for federal estate-tax reporting, but the assignment’s intended use should be clear. For an estate required to file IRS Form 706, the report’s date, asset description, method, and conclusion can help connect the appraisal to the filing. The appraiser’s opinion remains distinct from legal or tax advice, which is why executors often work alongside trust and estate administration specialists like Sheikh Najam TEP to navigate the broader estate and tax compliance process.
When several assets are involved, each item should be identifiable in the report. A home and a separate parcel of land, for example, shouldn’t be confused under one unexplained value. Clear descriptions and separate conclusions, where applicable, help the executor track estate assets and share information with beneficiaries. Supporting data lets readers follow the reasoning, not just the final number.
USPAP-compliant reports are used in matters involving the IRS, probate courts, and financial institutions. Their structure can help heirs present a documented opinion for estate purposes while keeping the value tied to its scope and effective date. A thorough report supports informed review; it doesn’t promise that every beneficiary, court, or agency will reach the same view.
Estate and probate appraisals
An estate appraisal gives an executor a documented opinion of an asset’s value for probate administration, distribution discussions, or tax purposes. In Orlando, its usefulness depends on matching the effective date and scope to the estate’s needs. A current sale decision, date-of-death valuation, and federal tax return may call for different valuation details.
Probate proceedings can involve distributing property among beneficiaries or preparing an asset for sale. A well-supported appraisal establishes a reasoned value rather than treating an online estimate or asking price as the estate’s established market value. It can also help the executor explain how the value was developed using property information and market evidence relevant to the assignment.
The appraiser selects an approach suited to the property and available evidence. For a typical home, the sales comparison approach considers comparable properties and adjusts for relevant differences. The building-cost approach considers the cost of constructing a similar building, land costs, and depreciation. For an income-producing property, the income approach considers income, operating expenses, and an expected rate of return.
These methods help explain why a single number may not capture every feature of an estate asset. Two Orlando homes with similar layouts, for example, may differ in condition, location, or improvements. The report should connect its value conclusion to those characteristics and explain which comparable sales or other evidence influenced the analysis. That reasoning gives beneficiaries a basis for reviewing the result.
Timing matters if the estate plans to sell the property. A listing price reflects a sale strategy, while an appraisal estimates value for its stated purpose and effective date. If the estate needs a date-of-death figure, later renovations or market changes shouldn’t be mistaken for conditions at the valuation date. Records of the home’s earlier condition can help the appraiser assess that historical context.
For tax purposes, an appraisal may support the value reported for estate assets; an estate large enough to require federal Form 706 needs a qualified appraisal. The report doesn’t prepare the return, but its property description, valuation date, method, and supporting evidence can help connect the stated value to the asset. Keep the report with estate records so the executor can refer to the same documented conclusion during administration.
If the estate needs a property valuation for probate or a planned sale, request an inherited-property appraisal with a clear purpose and effective date. A well-defined assignment helps align the report with the estate’s actual question, whether that concerns historical value, current market evidence, or a contemplated sale.
Meridian Property Appraisers
Meridian Property Appraisers Inc. provides Pre-Probate Inherited Properties Appraisals for heirs who need a documented property valuation before estate decisions move forward. A clear assignment identifies the property, valuation date, and purpose, giving beneficiaries a shared report to discuss when opinions differ. If the estate is preparing a home for sale, a Pre-Listing Appraisal addresses that separate valuation need.
For an appraisal for multiple heirs in an Orlando estate, Meridian Property Appraisers Inc. can provide a consistent reference for the executor and beneficiaries without replacing legal or tax advice. The report can distinguish a value for estate purposes from expectations about a future listing. Request an appraisal online or call Meridian Property Appraisers Inc. to discuss the inherited property.
Set a Clear Direction for the Estate
Before the next family discussion, identify the decision the valuation needs to support. Is the estate preparing to distribute the property, considering a sale, or documenting value for another purpose? A shared objective helps heirs, the executor, and the appraiser begin with the same expectations.
For an appraisal for a multiple-heir estate in Orlando, Meridian Property Appraisers Inc. provides a Pre-Probate Inherited Properties Appraisal. Other relevant offerings include Pre-Listing Appraisals and Divorce Appraisals, each for a distinct valuation need. Start by identifying the property’s intended use and the question the report must answer.
When you’re ready to discuss the estate’s valuation needs, contact Meridian Property Appraisers Inc. A focused conversation can help you determine the next appraisal step and move forward with greater clarity.
Frequently Asked Questions
What Is the Cost of an Appraisal?
The fee depends on the assignment and is provided after a quote request. Property size, location, timing, and the work needed to answer the valuation question affect the cost. A retrospective appraisal, for example, requires analysis tied to a past valuation date, while a current valuation addresses different market evidence. Define the property and intended use clearly so the quote reflects the appraisal scope.
Do You Need Separate Appraisals for Date-of-Death Value and Listing Price?
Separate assignments may be appropriate because date-of-death value and listing price address different dates and purposes. A retrospective appraisal estimates value at the owner’s death; a listing-focused appraisal addresses the property’s market value for a sale decision. If the home changed after the owner died, the effective date and assignment scope help distinguish historical value from current conditions and sale expectations.
What Are the Different Types of Appraisal for Estate Purposes?
Estate appraisals can address historical value, current property value, or a tax valuation purpose. A date-of-death appraisal focuses on value when the owner died, while an appraisal for a planned sale considers the relevant current market. The appropriate type depends on the estate’s decision and the report’s intended use. State the purpose at the outset so the valuation answers the right question.
What Happens If the Property Changed After the Owner Died?
The appraisal should distinguish the home’s condition on the valuation date from its condition today. If heirs replaced a roof after the owner’s death, for example, that improvement shouldn’t be treated as though it existed on the earlier date. Photos, renovation records, and other dated documentation can help establish the property’s prior condition. The appraiser then analyzes evidence relevant to the requested effective date.
What Influences the Price?
An appraisal fee depends on the property’s size, location, timing, and assignment scope, and is provided after a quote request. A single Orlando residence and a complex property assignment require different levels of inspection and analysis. A historical valuation may also require research into past market conditions. Clear information about the property, effective date, and intended use helps define the work included in the quote.
What Is a Certified Appraisal for an Estate Sale?
For an estate sale, a formal appraisal report documents an appraiser’s value opinion and explains its basis. The report should identify the property, valuation date, method, appraiser qualifications, and supporting evidence. “Certified” shouldn’t be treated as a guarantee that every heir will agree or that a buyer will pay the appraised amount. Its practical value is a documented analysis for the stated estate purpose.
How Much Does an Estate Appraisal Cost in Orlando, Florida?
The fee depends on the property and assignment, and is provided after a quote request. Property size, location, timing, and whether the valuation is historical affect the work involved. Meridian Property Appraisers Inc. serves Orlando and other Florida locations, including Tampa, Saint Petersburg, Jacksonville, Clearwater, Largo, Pinellas Park, Seminole, Miami, and Fort Lauderdale. A quote should reflect the specific property and intended use.
What Types of Estate Appraisals Are Available for Homes, Personal Property, and Businesses?
Homes, personal property, and business interests are distinct asset categories, so the appraisal scope should identify exactly what needs valuation. A home appraisal addresses real estate; vehicles and other personal property require asset-specific analysis, while a business interest presents a different valuation question. Meridian Property Appraisers Inc. offers a Pre-Probate Inherited Properties Appraisal for inherited property. Clearly identifying the asset helps keep the assignment focused.
Comments